
Note: This article is based on real U.S. household wealth data from reputable financial and government sources, rewritten in original language for web publishing.
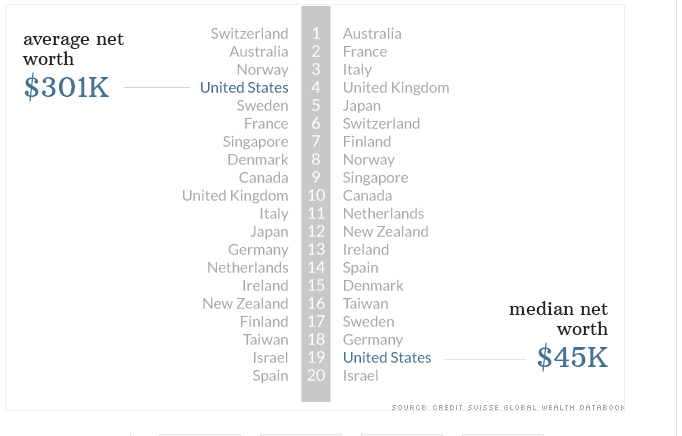
The average American net worth sounds enormous at first glance. Depending on the data set, the average household may appear to be sitting on a seven-figure balance sheet, wearing a tiny top hat, and casually sipping coffee beside a portfolio full of real estate, retirement accounts, and stocks. But before anyone starts checking the couch cushions for a missing million dollars, there is an important catch: averages can be wildly misleading.
In America, wealth is not spread like peanut butter on toast. It is more like chunky peanut butter dropped from a helicopter. Some households own very little. Others own businesses, multiple homes, investment portfolios, and enough appreciated stock to make a calculator wheeze. That is why the average American net worth is huge, while the median American net worth tells a much more down-to-earth story.
The idea behind the Financial Samurai approach is simple: do not blindly compare yourself with the national average and then either panic or celebrate. Instead, understand what the numbers mean, why wealth is so unevenly distributed, and how disciplined saving, investing, career growth, home equity, and smart debt management can move your own net worth in the right direction.
What Is Net Worth?
Net worth is the value of everything you own minus everything you owe. The formula is refreshingly simple:
Net worth = assets – liabilities.
Assets include cash, checking accounts, savings accounts, retirement plans, brokerage investments, real estate, business equity, vehicles, and other valuable property. Liabilities include mortgages, student loans, auto loans, credit card balances, personal loans, medical debt, and other financial obligations.
For example, imagine a household owns a $500,000 home, has $120,000 in retirement accounts, $30,000 in cash and investments, and a $20,000 car. That is $670,000 in assets. If the household also owes $300,000 on the mortgage, $15,000 on the car, and $10,000 in credit card debt, liabilities total $325,000. The household’s net worth is $345,000.
That number does not mean the family has $345,000 sitting in a checking account ready for an emergency pizza party. A lot of net worth may be locked inside home equity or retirement accounts. Still, it gives a useful snapshot of financial progress.
Why the Average American Net Worth Looks So Huge
The average U.S. household net worth is heavily pulled upward by high-net-worth households. When a billionaire walks into a room of regular people, the average net worth of the room suddenly becomes ridiculous. Nobody else got richer, but the spreadsheet is now wearing sunglasses.
That is why median net worth is usually more useful for everyday comparison. The median represents the midpoint: half of households have more, and half have less. According to recent Federal Reserve Survey of Consumer Finances data, the average family net worth was above $1 million, while the median was under $200,000. That huge gap shows exactly how concentrated wealth can be.
So when people say, “The average American is a millionaire,” they are using a technically true but emotionally dangerous sentence. It is like saying the average temperature between your freezer and your oven is comfortable. Mathematically, sure. Practically, please do not sit there.
Average vs. Median Net Worth: The Most Important Distinction
The average is calculated by adding all household net worth figures together and dividing by the number of households. The median lines everyone up from poorest to richest and picks the household in the middle.
Why Average Net Worth Can Mislead
Average net worth is useful for understanding national wealth, asset growth, and broad economic trends. But it is not always useful for personal benchmarking because the very wealthy dramatically shift the number upward.
If ten households are in a neighborhood and nine have a net worth of $100,000 while one has $50 million, the average net worth is over $5 million. But nine out of ten households are nowhere near that. The median would still be $100,000, which better represents the typical household.
Why Median Net Worth Feels More Realistic
Median net worth better answers the question most people actually have: “Where do I stand compared with a typical household?” It removes the distortion created by extreme wealth at the top.
That does not mean average net worth is useless. It simply means it should be treated like hot sauce: powerful, interesting, and dangerous when dumped everywhere without thinking.
Average American Net Worth by Age
Net worth usually rises with age because people have more years to earn, save, invest, pay down debt, and benefit from home appreciation and compound growth. Younger households often have lower net worth because they may be dealing with student loans, entry-level salaries, childcare costs, or the great financial mystery known as “why did groceries cost $87 when I bought only five things?”
| Age Group | Average Net Worth | Median Net Worth |
|---|---|---|
| Under 35 | About $183,500 | About $39,000 |
| 35-44 | About $549,600 | About $135,600 |
| 45-54 | About $975,800 | About $247,200 |
| 55-64 | About $1.57 million | About $364,500 |
| 65-74 | About $1.79 million | About $409,900 |
| 75+ | About $1.62 million | About $335,600 |
The pattern is clear: net worth tends to build over decades. The biggest jumps often happen after middle age, when career earnings may be higher, retirement contributions have compounded, and mortgage balances may be lower.
The Financial Samurai Lesson: Aim Above Average, But Think Clearly
The Financial Samurai philosophy encourages people to be proactive rather than passive. The goal is not to stare at a national average and feel either superior or doomed. The goal is to build a plan that makes your future self send your current self a thank-you card.
An “above average” financial path usually includes several behaviors: earning intentionally, saving consistently, investing early, avoiding lifestyle inflation, building multiple assets, tracking net worth, and refusing to let debt grow like an unattended houseplant.
Beating the average is not always about making a giant salary. A high income helps, of course. Money is easier to save when there is more of it, a concept economists have studied carefully and everyone else calls “obvious.” But income alone does not create wealth. Wealth comes from converting income into assets.
What Actually Builds American Net Worth?
1. Home Equity
For many American households, the primary home is the largest asset. Homeownership has historically helped families build wealth through forced savings, mortgage paydown, and price appreciation. Every mortgage payment can gradually shift money from debt to equity.
However, homeownership is not magic. Homes require maintenance, insurance, taxes, repairs, and occasionally a water heater that chooses violence on a Sunday night. Buying too much house can slow wealth building if the monthly payment leaves little room for investing.
2. Retirement Accounts
401(k)s, IRAs, Roth IRAs, 403(b)s, and similar retirement accounts are major wealth-building tools. They offer tax advantages, automatic payroll contributions, employer matches, and long-term compounding.
The simplest winning move is often boring: contribute regularly, capture the employer match if available, increase the contribution rate over time, and avoid raiding the account early. Boring is underrated. A boring investment plan often beats an exciting one in the same way a seatbelt beats a motorcycle stunt.
3. Stocks and Investment Funds
Stocks have played a major role in U.S. household wealth growth, especially for higher-income households. Index funds, mutual funds, ETFs, and retirement portfolios allow regular investors to own small pieces of large companies.
The challenge is staying invested through downturns. Markets do not rise in a straight line. They rise, fall, scare everyone, recover, and then repeat the drama with new headlines. Long-term investors usually benefit from patience, diversification, and resisting the urge to treat every market dip like a meteor strike.
4. Business Ownership
Business equity can be a powerful wealth accelerator. Many wealthy households own private businesses, professional practices, real estate partnerships, or side businesses that grow beyond ordinary wages.
Not everyone needs to start a company. But developing income-producing skills, freelancing, consulting, or creating a small business can add flexibility and increase savings power.
5. Debt Control
Debt can either help or hurt net worth depending on how it is used. A reasonable mortgage on an appreciating home may support wealth building. High-interest credit card debt does the opposite. It is like trying to fill a bathtub while the drain is open and a raccoon is stealing your towels.
Reducing expensive debt gives households more room to invest, save, and breathe.
Why Many Americans Feel Poor Despite High Average Wealth
One reason the average American net worth feels disconnected from daily life is that wealth is not the same as cash flow. A household may have $400,000 in home equity but still struggle with monthly bills if income is tight and expenses are high.
Inflation, healthcare costs, childcare, housing prices, student debt, insurance premiums, and transportation costs can make even decent earners feel financially squeezed. A rising net worth does not automatically mean life feels easy.
Another issue is liquidity. Home equity and retirement accounts are valuable, but they are not always easy to access without selling, borrowing, paying taxes, or facing penalties. This is why emergency savings still matter. A family with a large retirement balance but no cash cushion may still be one broken transmission away from financial stress.
How to Increase Your Net Worth Without Becoming a Spreadsheet Monk
Track Your Net Worth Quarterly
You do not need to check your net worth every morning like it is a needy houseplant. Quarterly tracking is enough for most people. List assets, subtract liabilities, and watch the trend over time.
Automate Saving and Investing
Automation removes the need for heroic willpower. Set retirement contributions, recurring transfers, and automatic investments. The less you rely on motivation, the better. Motivation is great, but it also disappears when there is pizza.
Increase Your Savings Rate Gradually
Try raising your savings rate by 1% whenever you get a raise. This small habit can make a large difference over decades without causing immediate lifestyle shock.
Own Appreciating Assets
Cash is useful for emergencies, but long-term wealth usually comes from assets that can grow: stocks, real estate, business equity, and retirement investments.
Avoid Lifestyle Inflation
As income rises, it is tempting to upgrade everything: car, apartment, vacations, gadgets, coffee, dog shampoo, and possibly the dog. Some lifestyle improvement is fine. But if every raise becomes a new payment, net worth may barely move.
Specific Example: Two Households, Two Outcomes
Consider two households earning similar incomes. Household A saves 5%, carries credit card debt, buys new cars frequently, and invests only when the market feels “safe.” Household B saves 20%, buys used cars, pays off high-interest debt, invests monthly, and increases retirement contributions after raises.
After 20 years, Household B may have a dramatically higher net worth even if both households earned similar salaries. The difference is not one magical decision. It is hundreds of small choices repeated until the numbers become loud.
Experience Section: What the Huge Average Net Worth Teaches in Real Life
Looking at the average American net worth can feel motivating, annoying, confusing, or all three before breakfast. The biggest lesson is that wealth building is not just about earning money. It is about keeping enough of it, investing it wisely, and giving time the chance to do its quiet, powerful work.
In real life, people often start paying attention to net worth after a financial wake-up call. Maybe they realize their income is good but their savings are strangely invisible. Maybe they get a raise and still feel broke six months later. Maybe they see a friend buy a house or retire early and wonder, “Wait, was there a meeting about money that I missed?”
The first useful experience is simply calculating net worth honestly. This can be uncomfortable. Nobody enjoys adding up credit card balances, student loans, car loans, and that one forgotten store card opened for 15% off a toaster. But clarity is powerful. Once the numbers are visible, they become manageable.
The second experience is learning that progress can be slow at first. In the early years, saving $200 or $500 a month may not feel impressive. The balance grows, but not dramatically. Then, after years of contributions and market growth, compounding begins to show its personality. The portfolio starts doing some of the work. Dividends appear. Retirement balances move by more in a month than you used to contribute in a year. That is when the boring plan starts looking suspiciously brilliant.
The third experience is discovering that comparison cuts both ways. Comparing yourself to billionaires is useless unless you need a quick way to ruin lunch. Comparing yourself with realistic age-based median numbers can be helpful. Comparing yourself with your own past behavior is even better. If your net worth is higher than last year, your debt is lower, your emergency fund is stronger, and your investments are growing, you are winning.
The fourth experience is realizing that lifestyle design matters. Some people build high net worth and still feel trapped because their expenses grew as fast as their assets. Others build moderate wealth but gain freedom because their spending is controlled, their debt is low, and their money supports their priorities. The point is not to collect dollars like arcade tickets. The point is to buy options: the option to change jobs, help family, retire earlier, travel, start a business, or sleep better at night.
The fifth experience is understanding that net worth is a long game. Markets will fall. Home repairs will happen. Cars will break. Kids will need things. Inflation will be rude. Life will occasionally throw a bowling ball into the spreadsheet. The solution is not perfection. The solution is resilience: cash reserves, diversified investments, reasonable insurance, flexible spending, and a habit of returning to the plan after disruptions.
That is the real Financial Samurai-style takeaway. The average American net worth may be huge, but your personal financial journey is not about worshiping a national statistic. It is about building a stronger balance sheet year after year. Track it. Improve it. Protect it. And when the average looks intimidating, remember: every large net worth started with the first dollar that did not get spent.
Conclusion
The average American net worth is huge, but the headline number hides a complicated reality. Averages are pulled upward by wealthy households, while median net worth gives a more realistic picture of the typical American family. The best approach is to understand both numbers, then focus on the factors within your control: income growth, saving rate, investing discipline, home equity, debt reduction, and long-term consistency.
Financial Samurai’s core message remains useful: do not settle for drifting with the crowd. Learn the numbers, track your own progress, and build wealth intentionally. You do not need to be perfect. You need a system that survives real life, market drama, inflation, and the occasional expensive surprise hiding in your garage.