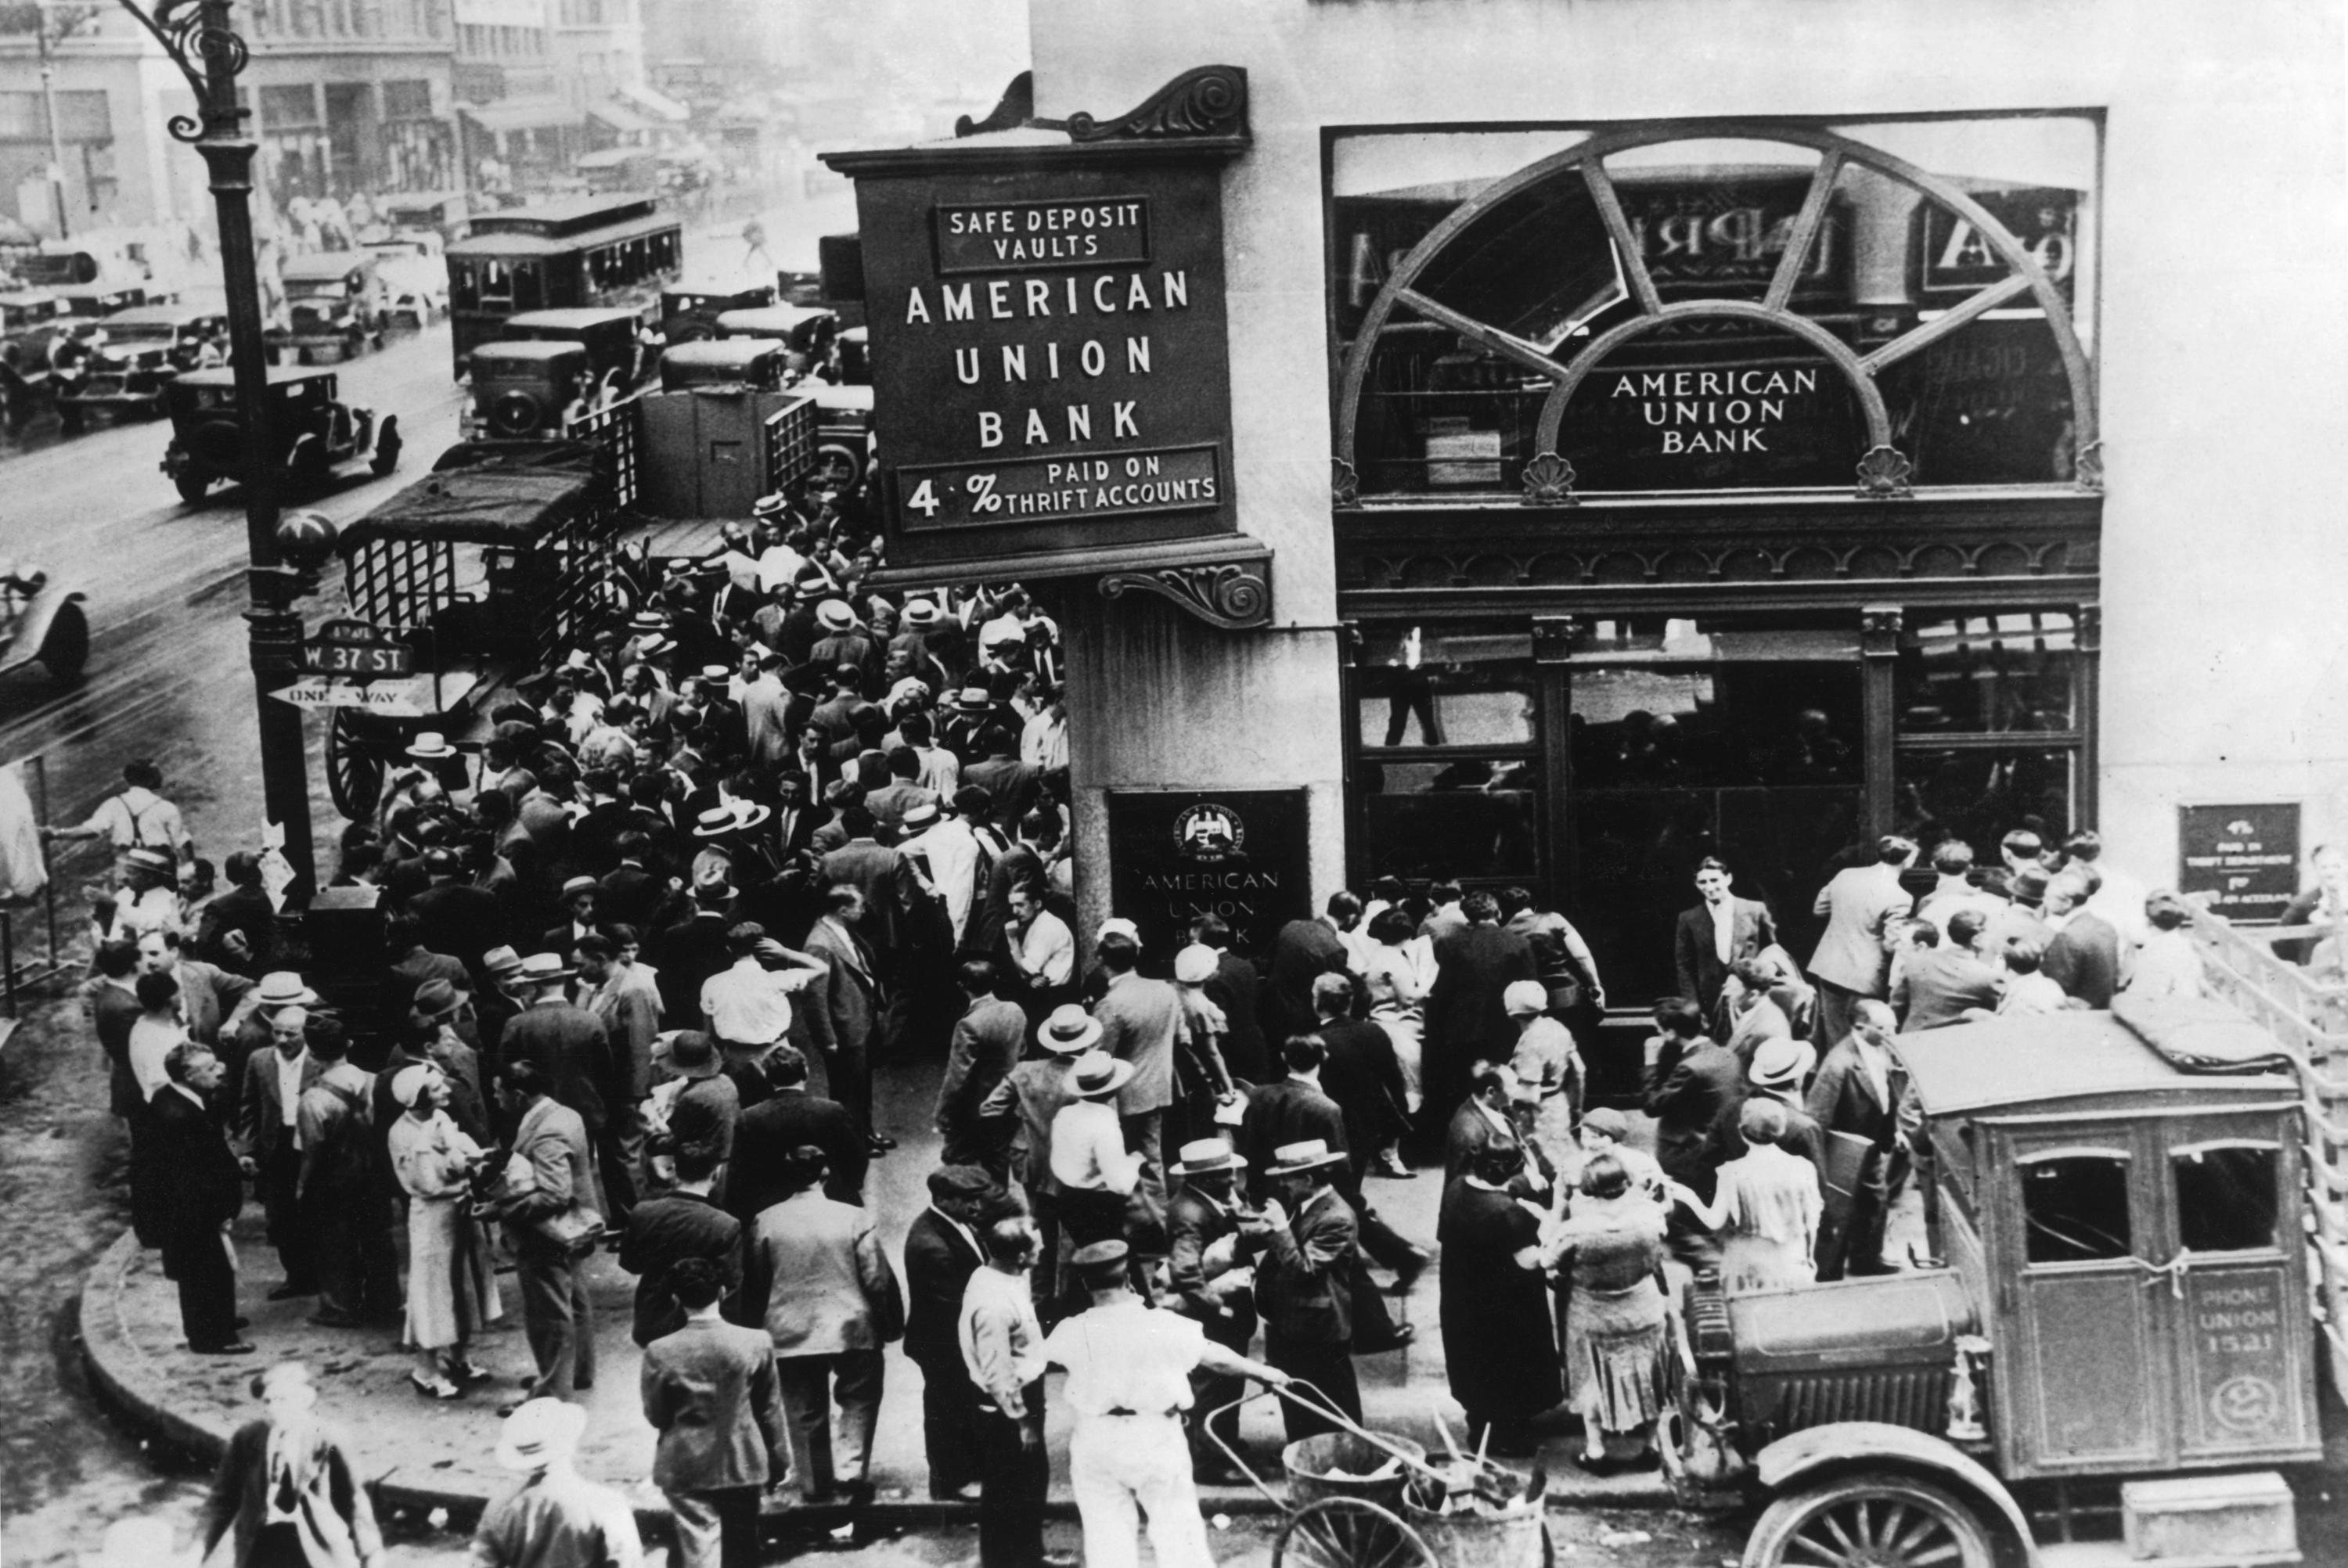

If money had a helmet, elbow pads, and a very serious government-issued badge, it would look a lot like FDIC deposit insurance. Since 1934, the Federal Deposit Insurance Corporation has helped Americans sleep better at night by protecting eligible bank deposits when an insured bank fails. The idea is simple: you should not have to sprint to the bank in a panic because a rumor, recession, or headline made everyone nervous before breakfast.
Today, most people know the big number: $250,000. But that number did not appear out of thin air. FDIC insurance limits have changed over time, moving from a modest $2,500 in 1934 to the modern $250,000 per depositor, per FDIC-insured bank, per ownership category. That phrase sounds like it was assembled by a committee with a strong coffee budget, but it matters. A lot.
This guide explains the history of FDIC deposit insurance limits, how coverage works, what “per bank account” really means, and how ordinary savers can avoid accidentally leaving money uninsured.
What Is FDIC Deposit Insurance?
FDIC deposit insurance is federal protection for eligible deposits held at FDIC-insured banks. If an insured bank fails, the FDIC steps in to protect depositors up to the applicable insurance limit. This protection applies automatically. You do not need to sign up, buy a policy, or find a tiny checkbox hidden beneath 47 pages of banking paperwork.
The FDIC was created during the Great Depression, when bank failures shook public confidence in the financial system. Before deposit insurance, many families lost savings when banks closed. The FDIC’s mission was to restore trust, discourage bank runs, and keep the banking system from turning into a national game of financial musical chairs.
What FDIC Insurance Covers
FDIC insurance generally covers deposit products at insured banks, including checking accounts, savings accounts, money market deposit accounts, certificates of deposit, cashier’s checks, and certain other official bank-issued items.
What FDIC Insurance Does Not Cover
FDIC insurance does not cover stocks, bonds, mutual funds, annuities, life insurance policies, municipal securities, crypto assets, safe deposit box contents, or losses from market movements. A savings account is protected against bank failure; your risky “I heard about this coin from a guy on the internet” investment is not. The FDIC is powerful, but it is not a magician in a cape.
FDIC Deposit Insurance Limits From 1934 to 2022
The FDIC insurance limit has increased several times since the program began. These increases usually reflected inflation, changes in banking behavior, economic stress, and the need to maintain confidence in the banking system.
| Year | FDIC Insurance Limit | What Changed |
|---|---|---|
| January 1, 1934 | $2,500 | Initial FDIC coverage began. |
| July 1, 1934 | $5,000 | The limit doubled within the first year. |
| 1950 | $10,000 | Coverage increased after years of economic growth. |
| 1966 | $15,000 | The limit rose to reflect larger balances and inflation. |
| 1969 | $20,000 | Congress raised protection again as deposits grew. |
| 1974 | $40,000 | The limit doubled during a period of economic uncertainty. |
| 1980 | $100,000 | A major increase arrived during high inflation and financial stress. |
| 2006 | $100,000 standard; $250,000 for certain retirement accounts | Some retirement accounts received higher protection. |
| 2008 | $250,000 temporary standard limit | The financial crisis triggered a temporary increase. |
| 2010–2022 | $250,000 standard limit | The $250,000 standard limit became permanent and remained in place through 2022. |
Why the FDIC Limit Increased Over Time
The original $2,500 limit in 1934 may look tiny today, but it was meaningful during the Great Depression. Back then, many households had far less cash in the bank than modern families may keep for emergency funds, down payments, business reserves, or retirement planning. As wages, prices, and account balances rose, Congress periodically raised the FDIC insurance limit.
The biggest jump came in 1980, when the standard coverage limit rose to $100,000. That increase happened during an era of high inflation, intense competition for deposits, and financial pressure across the banking industry. Then, during the 2008 financial crisis, the limit temporarily rose to $250,000 to calm fears and strengthen depositor confidence. In 2010, that $250,000 standard maximum deposit insurance amount became permanent.
What “Per Depositor, Per Bank, Per Ownership Category” Means
The phrase “$250,000 per depositor, per FDIC-insured bank, per ownership category” is the key to understanding FDIC coverage. It does not simply mean every bank account gets its own separate $250,000 shield. Coverage depends on who owns the money, where it is held, and how the account is legally titled.
Per Depositor
A depositor is the person or legal entity that owns the funds. If you have an individual savings account and an individual checking account at the same bank, both accounts belong to the same depositor in the same ownership category.
Per FDIC-Insured Bank
The limit applies separately at each FDIC-insured bank. If you have $250,000 at Bank A and $250,000 at Bank B, and both banks are FDIC-insured, each balance may be separately insured. However, two branches of the same bank do not count as two separate banks. Moving money from one branch to another branch of the same institution is not a clever loophole; it is just a scenic tour of the same coverage limit.
Per Ownership Category
Ownership categories are the secret sauce. FDIC rules recognize different categories, such as single accounts, joint accounts, certain retirement accounts, trust accounts, employee benefit plan accounts, business accounts, and government accounts. Deposits in different ownership categories may qualify for separate coverage at the same bank if requirements are met.
Examples of FDIC Coverage in Real Life
Example 1: One Person, One Bank, Two Single Accounts
Suppose Maria has $100,000 in checking and $200,000 in savings at the same FDIC-insured bank. Both are single accounts owned by Maria. The FDIC adds them together for the single-account ownership category. Her total is $300,000, so $250,000 is insured and $50,000 may be uninsured.
Example 2: One Person, Two Banks
Now suppose Maria keeps $250,000 at Bank A and $250,000 at Bank B. If both are FDIC-insured banks and both accounts are properly titled, she may have $500,000 of total coverage because the limit applies separately at each insured bank.
Example 3: Married Couple With Individual and Joint Accounts
Consider Alex and Jordan. Alex has $250,000 in a single account. Jordan has $250,000 in a single account. Together, they also have $500,000 in a joint account at the same FDIC-insured bank. Because single and joint accounts are different ownership categories, and each joint owner can receive coverage for their ownership interest, the couple may have up to $1 million insured at one bank if the accounts meet FDIC rules.
Why “Per Bank Account” Can Be Misleading
The title phrase “FDIC deposit insurance limits per bank account” is popular because it sounds practical. But technically, FDIC insurance is not simply calculated per account. The FDIC looks at ownership category and bank relationship. This means having five savings accounts in your own name at the same bank does not automatically give you five separate $250,000 limits.
Think of it like a closet. If you buy five shoeboxes and put them all in the same closet, you still have one closet. FDIC coverage works similarly: multiple accounts in the same ownership category at the same insured bank are grouped together. If you want more insured coverage, you usually need different ownership categories, different insured banks, or both.
How to Check Whether Your Bank Is FDIC-Insured
Before opening an account, confirm that the institution is FDIC-insured. You can usually find FDIC membership information on the bank’s website, at branch locations, and in official disclosures. The FDIC also provides BankFind, a tool that helps consumers verify whether a bank is insured.
This step is especially important when using online banks, financial apps, or fintech platforms. Some apps are not banks themselves. They may partner with FDIC-insured banks, but coverage can depend on how the funds are held, titled, and recorded. If the marketing copy sounds like it was written by a glitter cannon, slow down and verify the details.
Using the FDIC’s EDIE Calculator
The FDIC’s Electronic Deposit Insurance Estimator, commonly called EDIE, helps depositors estimate coverage across banks and ownership categories. It can be especially useful for households with multiple accounts, CDs, trust accounts, retirement deposits, or business funds.
EDIE is not a replacement for professional advice in complicated cases, but it is a strong starting point. It helps turn a confusing pile of account balances into a clearer picture of what may be insured and what may exceed the limit.
Common FDIC Insurance Mistakes
Mistake 1: Assuming Every Account Gets $250,000
This is the classic misunderstanding. A checking account and savings account owned by the same person at the same bank are not separately insured for $250,000 each if they are both in the same ownership category.
Mistake 2: Forgetting About Accrued Interest
FDIC coverage includes principal and accrued interest up to the insurance limit. If your CD grows past $250,000 because of interest, the excess may not be insured. Interest is wonderful, but it can quietly nudge you over the line like a polite but determined golden retriever.
Mistake 3: Confusing FDIC and NCUA Insurance
Banks are insured by the FDIC. Federally insured credit unions are protected by the National Credit Union Share Insurance Fund, administered by the NCUA. The protection is similar in purpose, but the agencies and rules are not identical.
Mistake 4: Assuming Investments Are Covered
If you buy stocks, mutual funds, bonds, annuities, or crypto through a bank-affiliated platform, FDIC insurance generally does not protect those products. The bank logo does not turn a market investment into a deposit account.
How Savers Can Stay Within FDIC Limits
For most households, FDIC limits are more than enough for everyday checking and savings. But people with large emergency funds, home-sale proceeds, inheritance money, business cash, or high CD balances may need to plan carefully.
Common strategies include spreading funds across multiple FDIC-insured banks, using different ownership categories when appropriate, monitoring CD interest, and periodically reviewing account titles. The goal is not to make banking complicated. The goal is to prevent a surprise uninsured balance from quietly sitting in the corner wearing sunglasses.
What the 1934–2022 FDIC Timeline Teaches Us
The FDIC insurance limit history tells a larger story about American banking. In 1934, the government’s priority was stopping bank runs and restoring public faith. By 1950 and the postwar decades, the goal expanded to reflect rising wealth and larger deposits. By 1980, inflation and banking competition pushed the limit to $100,000. By 2008 and 2010, the financial crisis showed how quickly confidence can evaporate when people fear their money is unsafe.
Through 2022, the $250,000 limit remained the standard. While discussions about inflation and future increases continued, the core structure stayed the same: deposit protection depends on depositor, bank, and ownership category.
Experience Notes: What FDIC Deposit Insurance Feels Like in Real Life
Reading about FDIC limits is one thing. Actually organizing money around them is another. Many people first care about FDIC insurance during a big financial transition. Maybe they sold a house, received an inheritance, built a successful business account, or saved aggressively for a down payment. Suddenly, the checking account that once held grocery money is carrying a balance that looks like it needs its own seatbelt.
One practical experience is the “temporary pileup” problem. Imagine selling a home and receiving $420,000 in proceeds. You park the funds in one savings account while shopping for the next house. It feels temporary, so it feels harmless. But if that balance sits in a single ownership category at one bank, part of it may exceed the standard FDIC limit. A simple fix might be moving some funds to another FDIC-insured bank or using a properly structured account category, but the key is noticing the issue before it becomes a problem.
Another common experience involves CDs. Savers love certificates of deposit because they are predictable. You put money in, you earn interest, and the account behaves better than most houseplants. But a $248,000 CD can grow above $250,000 after interest accrues. That does not mean CDs are bad; it means savers should calculate the ending balance, not just the opening deposit.
Business owners often face a different challenge. Payroll, vendor payments, tax reserves, and operating cash can easily push balances above the FDIC limit. A small business owner may keep money in one bank for convenience, only to discover that convenience and full insurance coverage are not always the same thing. Reviewing business account balances monthly can help identify when deposits should be spread out or restructured.
Families also learn that account titles matter. A parent might add an adult child to an account for convenience, or a couple might open several accounts without thinking about ownership categories. These choices can affect coverage. Good recordkeeping, clear account titles, and occasional reviews can prevent confusion later.
The biggest lesson from real-life FDIC planning is this: deposit insurance is not scary, but it is specific. It rewards clarity. Know the bank. Know the owner. Know the category. Know the balance. Once those pieces are clear, FDIC insurance becomes less like a mystery and more like a practical safety checklist.
Conclusion
FDIC deposit insurance has been one of the quiet stabilizers of American banking since 1934. The limit has grown from $2,500 to $250,000, reflecting nearly a century of inflation, banking changes, and economic shocks. But the most important rule is not just the dollar amount. It is how the coverage is calculated: per depositor, per FDIC-insured bank, per ownership category.
For everyday savers, that means checking account titles, understanding ownership categories, verifying FDIC-insured institutions, and using tools like EDIE when balances get large. FDIC insurance will not make you rich, pick your investments, or stop you from buying overpriced coffee. But it can protect eligible deposits from bank failure, and that makes it one of the most important financial safety nets in the United States.
SEO Tags
Note: This article is for educational content publishing only and should not be treated as personalized financial, legal, or banking advice. Readers with large balances, business deposits, trust accounts, or complex ownership structures should verify coverage directly with the FDIC, their bank, or a qualified financial professional.